The 1947 Soviet Monetary Reform: Cash, Savings and Ration Cards
How the 1947 Soviet reform treated cash, deposits, wages and ration cards differently. Worked savings examples explain the rules in the original documents.
The Soviet monetary reform of 1947 began on 16 December. Paper cash was exchanged at ten old rubles for one new ruble, but savings deposits followed a different schedule and wages were not divided by ten. At the same time, the government abolished ration cards for food and manufactured goods.
The interaction of these rules is the key to understanding the reform. Equal sums kept at home and held in a savings account could emerge as very different amounts of new money. Describing the operation as simply removing a zero from the currency misses what happened to accumulated savings.
What the government announced
Resolution No. 4004 of the USSR Council of Ministers and Communist Party Central Committee was adopted on 14 December 1947. It linked monetary reform to the consequences of war, excess money in circulation and the transition to trade without ration cards. These were the government's stated objectives, which should be distinguished from the effects on particular households.
The resolution emphasized speculative fortunes accumulated during the war. The exchange rule itself, however, did not investigate how each banknote had been obtained. Legally earned cash savings were affected too. Our broader history of the Soviet ruble provides context; this article focuses on the specific mechanisms introduced in December 1947.
The postwar setting also matters. The end of fighting did not instantly restore output and distribution. A monetary operation could alter the quantity of purchasing means, but it could not itself produce food, clothing or housing. Money and the supply of goods have to be considered together.
Paper cash and coins were treated differently
The exchange began on 16 December and was generally to be completed within one week. Specified remote areas received a two-week period. Old banknotes not presented within the prescribed period lost their payment value. A separate Finance Ministry instruction detailed how exchange points and the acceptance of old currency would operate.
Small change remained in circulation at its existing face value. Even the term cash therefore needs care: the ten-to-one rule applied to paper currency, not indiscriminately to everything in a purse.
During the exchange period, old notes could still be used for payments, but at one tenth of their face value. A hundred old rubles represented ten new rubles. Spending an old note rather than exchanging it was consequently not a way to preserve its former nominal purchasing amount.
The administrative arrangements went beyond bank counters. The instruction allowed designated savings offices, postal facilities and other authorized payment points to participate. It even addressed exchange arrangements on certain long-distance trains. Replacing currency was a logistical undertaking as well as a decision about conversion rates.
Deposits were revalued in bands
Deposits received more favorable treatment. The first 3,000 rubles were preserved at their nominal amount. The portion between 3,000 and 10,000 was converted at three old rubles for two new ones. Any portion above 10,000 was converted at two for one.
The crucial detail is that these rates applied to portions of the balance. A deposit of 6,000 did not simply become 4,000. Its first 3,000 remained unchanged and the next 3,000 became 2,000, producing a new principal balance of 5,000.
These illustrative calculations exclude accrued interest:
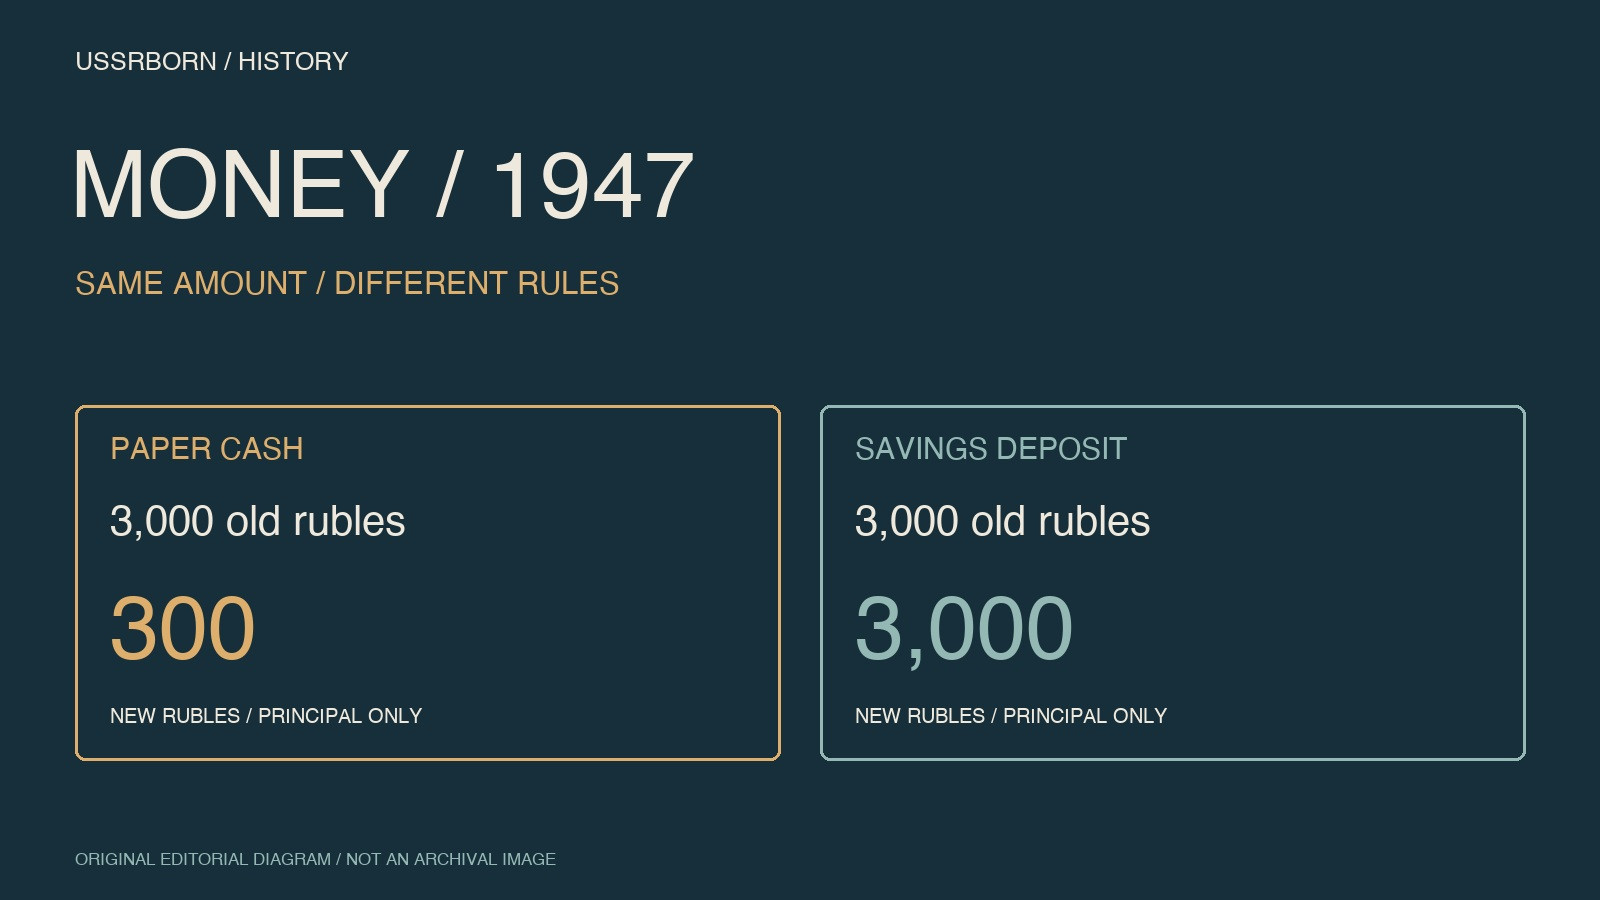
- Paper cash of 3,000 rubles became 300 new rubles; a deposit of 3,000 remained 3,000.
- A deposit of 6,000 became 5,000: 3,000 + 3,000 × 2/3.
- A deposit of 9,000 became 7,000: 3,000 + 6,000 × 2/3.
- A deposit of 12,000 became approximately 8,666.67: 3,000 + 7,000 × 2/3 + 2,000 × 1/2.
The last figure is rounded for explanation, not offered as a reconstruction of a particular bank entry. Interest for 1947 was subject to separate provisions. Reconstructing a real savings-book balance therefore requires more than knowing the amount of principal.
This comparison also shows why a single percentage cannot describe every household's experience. The loss depended on both the amount and the form in which savings were held. A family with a modest bank balance and one holding the same nominal sum in notes faced quite different outcomes.
Could cash be protected by depositing it after the announcement?
From 16 December, old currency paid into accounts was credited at one tenth of its face value. Once the reform had begun, bringing 3,000 old rubles to a savings office did not create a protected deposit of 3,000 new rubles.
The instruction also stated that when an institution knew a depositor held several accounts, revaluation was to be based on the combined amount. This establishes the intended rule. It does not prove that officials identified every instance of divided holdings, which is a separate question about implementation.
Deposit acceptance and withdrawal operations were suspended for 15 to 17 December and were to resume on 18 December. These dates help distinguish a balance that already existed at the relevant moment from cash introduced after conversion had started.
Such distinctions are useful when reading family recollections. The statement that someone had several thousand rubles is incomplete unless it specifies whether the money was held in banknotes, a deposit or securities, and when the relevant transaction occurred.
Wages and government bonds followed other rules
The resolution preserved the nominal amounts of wages and other specified labor incomes, now payable in new currency. It is consequently incorrect to apply the cash exchange rate to the whole income system and conclude that every monthly salary automatically fell by ninety percent.
Government loans were handled separately. A number of earlier bond issues were converted at three old rubles of bonds for one ruble of replacement bonds. The 1938 lottery loan had a five-to-one conversion, while the 1947 loan issue was excluded from conversion. Savings was therefore a broad category containing assets governed by different provisions.
Nor does the preservation of a salary's number establish the complete effect on living standards. Prices, goods available for purchase and the household's accumulated resources all matter. The article on Soviet wages and prices places that question in a wider setting.
A flow of future income and a stock of past savings are not the same thing. A worker could retain the nominal monthly wage while losing a large part of previously saved paper cash. Treating one result as proof that the other did not occur obscures the operation of the reform.
What ending ration cards meant
The government replaced rationed distribution and state commercial sales with a unified system of state retail prices. This did not mean that every product's price changed by the same proportion. The resolution specified different treatment for different groups: some former ration prices were reduced, some retained, and other prices were set at a new level.
The specified prices also did not apply to collective-farm markets or cooperative sales of goods from their own purchases. Statements that all prices became uniform therefore need to identify the boundaries of the state retail system being discussed.
Ending cards changed access to purchases but did not, by itself, demonstrate that shortages had disappeared. Money, an available product and a ration entitlement are different elements of distribution. Removing the entitlement requirement did not automatically supply either money or goods to every household.
The Pechora museum's surviving 1947 bread card is a reminder that rationing was an administrative practice involving actual documents. An object of that kind helps connect the monetary decision to the ordinary procedures through which people obtained necessities.
How to assess the reform
The reform was not a neutral conversion of every amount at one common rate. Paper cash, deposits, bonds and current incomes were treated differently. That conclusion follows directly from the rules, without assuming identical losses for all citizens.
For a household history, the relevant questions concern the size and form of savings and subsequent consumption conditions. For a state history, they concern monetary administration and the reorganization of trade within the planned economy. These perspectives can coexist: a measure intended to improve monetary control could also impose a substantial loss on someone holding cash savings.
The most reliable starting point is therefore a set of separate questions. What asset was involved? Which conversion rule applied? What happened to income? What could the resulting money buy? Keeping those questions distinct makes the reform more understandable than a single slogan about a stronger ruble or a removed zero.
Sources
- Resolution No. 4004 of 14 December 1947, the substantive rules. The electronic transcription contains a 1946 typo in its ration-card section; the event occurred in 1947.
- Finance Ministry instruction approved by Resolution No. 3860, operational rules and deposit calculations.
- Bank of Russia historical chronology, the reform in the history of monetary circulation.
- Pechora museum: a 1947 bread ration card, material evidence of rationing.
The cover is an original comparison diagram. Its cash and deposit amounts are illustrative.